Hospitality and lifestyle destinations set to spur luxury growth in Gulf states

Capitalizing on changes in the global luxury retail sector, the Middle East is rapidly solidifying its status as a primary investment hub by integrating high-end retail with massive hospitality pipelines and experiential lifestyle developments, according to the Global Luxury Retail Outlook 2026 from Savills.
Luxury brands are becoming significantly more selective when planning their global expansions. Meanwhile, the Middle East has been rapidly cementing its status as a primary hub for high-end retail investment. This upward trajectory is fueled by climbing wealth levels, major investments in high-end hospitality, and lifestyle-centered projects, reinforcing the long-term regional appeal of the market.
While global expansions have entered a much more deliberate and measured phase, retail experts note that this shift represents a calculated strategic transition rather than a decline in consumer interest. In fact, total new store openings across the globe dropped in 2025 to the lowest level recorded since 2020. This change occurred as premier brands intentionally prioritized top-tier locations capable of supporting their long-term market positioning.
The broad recalibration of the sector is evident in the slowdown of new luxury store activity last year. Though destination cities and global alpha cities both saw a slowdown, the extent of the contraction was less severe than in other market types. This relative resilience proves the importance of these locations for global luxury networks.
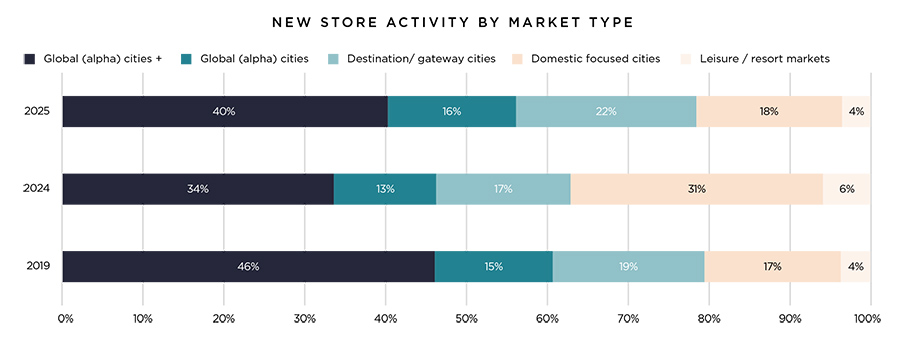
“The luxury retail sector is becoming increasingly focused on quality over quantity. Brands are prioritizing destinations that offer access to affluent consumers, strong tourism performance and a wider lifestyle proposition, rather than simply pursuing expansion for the sake of it,” said Thea Rowe, associate director at Savills.
“Over the years, Middle Eastern cities such as Dubai and Riyadh have evolved into global lifestyle destinations, where luxury retail is supported by world-class hospitality, branded residences, cultural attractions and a growing presence of high-net-worth individuals.”
Experiential ecosystems in Dubai and Riyadh
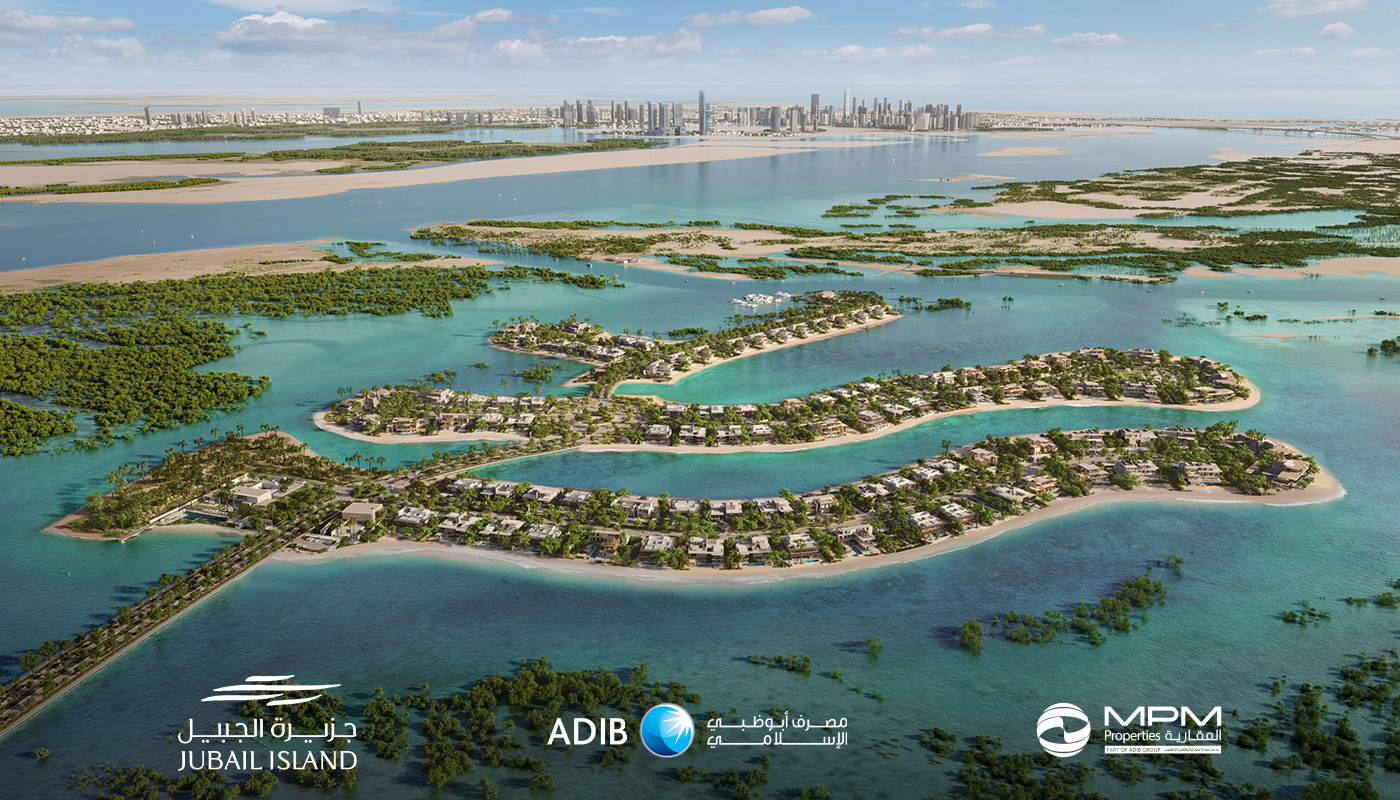
The luxury retail landscape across the Middle East is increasingly defined by an expansive ecosystem that blends traditional shopping with hospitality, branded residences, fine dining, and entertainment options. This transformation is highly visible in prominent hubs such as Dubai and Riyadh. In these destination cities, extensive investments in luxury hotels, waterfront properties, and mixed-use urban districts continue to draw substantial interest from international tourists and wealthy local residents alike.
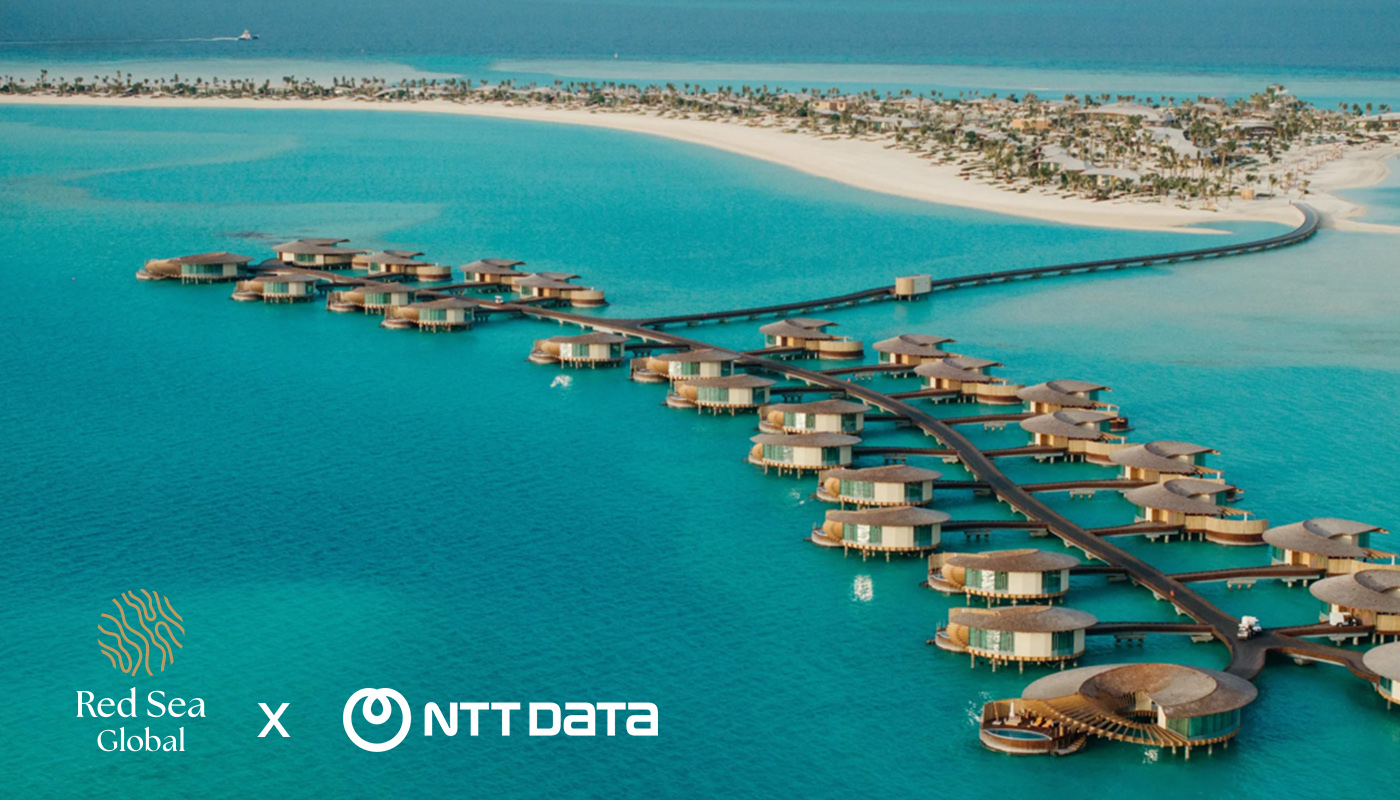
The research emphasizes that high-end hospitality plays an important role in directing future retail demand, with major destination hubs benefiting from massive luxury hotel construction pipelines. This development mirrors a prominent shift in modern consumer habits, where luxury expenditures are heavily tied to experiential activities during travel, rather than focusing solely on conventional shopping excursions.
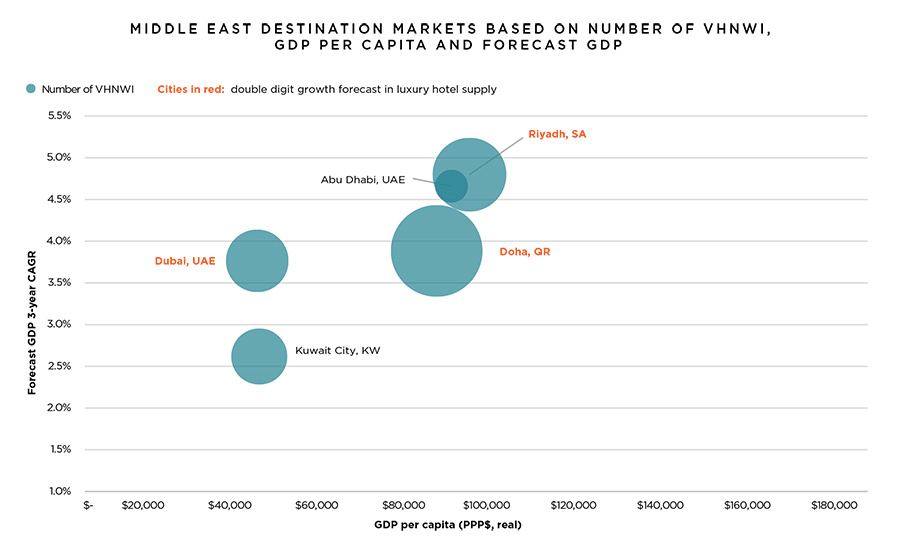
When it comes to very-high-net-worth individuals (VHNWIs), the GCC remains compelling over the medium to long term, supported by strong domestic wealth and growth prospects. Emerging tourist hubs beyond Dubai, like Riyadh and Doha, are supported by new hotel development. The challenge now is to navigate the ongoing conflicts in the region and emerge economically intact.
Long-term resilience overcomes regional pressures
Persistent geopolitical tensions across the region are currently impacting commercial flight paths and driving up aviation costs, which will likely limit international traveler volumes over the short term. In addition to that, there has been a serious shock to investor confidence in cities like Dubai, which have now been shown to be more vulnerable than previously thought.
Despite that, the medium and long-term economic foundations for the Middle East remain highly attractive, supported by deep domestic wealth pools and continuous capital deployment into luxury infrastructure developments.
This ongoing evolution is unlocking fresh commercial avenues outside of the traditional, long-established retail corridors. As experiential, project-led developments materialize throughout the region, elite brands are considering potential locations based on holistic visitor experiences, transport accessibility, and neighborhood amenities, according to Savills.
Riyadh serves as an example of this trend. The city is currently projected to experience the highest percentage growth in luxury hotel room capacity of any global market currently under construction. This massive pipeline is expected to reinforce the long-term retail prominence of the city alongside Dubai.
Looking forward, retail analysts expect high-end demand throughout the Middle East to stay resilient over the coming years, driven by robust local wealth, proactive government investment frameworks, and the enduring draw of the region for multinational corporate enterprises and wealthy individuals.
“The future of luxury retail is closely linked to the destinations consumers choose to live, stay and spend time in,” said Rowe. “The most successful locations will be those that combine retail with hospitality, culture and lifestyle, creating environments that encourage longer stays and deeper consumer engagement.”