Roland Berger: Gulf banks reduce bad loans, but underlying credit risks remain

Banks across the GCC have significantly reduced their non-performing loan ratios over the past five years. However, a new report from Roland Berger warns that the decline has been driven largely by favorable macroeconomic conditions, active balance-sheet management and write-offs, raising questions about how much of the improvement reflects structural gains in credit risk management.
Amidst the reduction in non-performing loans (NPLs), it remains unclear whether GCC banks have made real gains in resilience. As regulatory requirements tighten and geopolitical uncertainty continues, the report from the strategy consultancy notes just how important it is for senior decision-makers in the region to understand what is behind the purging of bad loans.
NPLs are loans that borrowers have failed to pay for 90 days or more, or that are otherwise unlikely to be repaid in full. A high NPL ratio can eat into a bank’s profits and limit how much new credit it can offer.
“A declining NPL ratio is a necessary but insufficient indicator of banking sector health. The question is whether the improvement is structural or cyclical,” said Santiago Castillo, senior partner and managing director at Roland Berger.
A mixed picture across three markets
The report focuses on the three largest banking markets in the region: Saudi Arabia, the UAE, and Qatar. The findings show their paths have looked very different, with Saudi and Emirati banks lowering their numbers of NPLs while Qatari banks now have more NPLs.
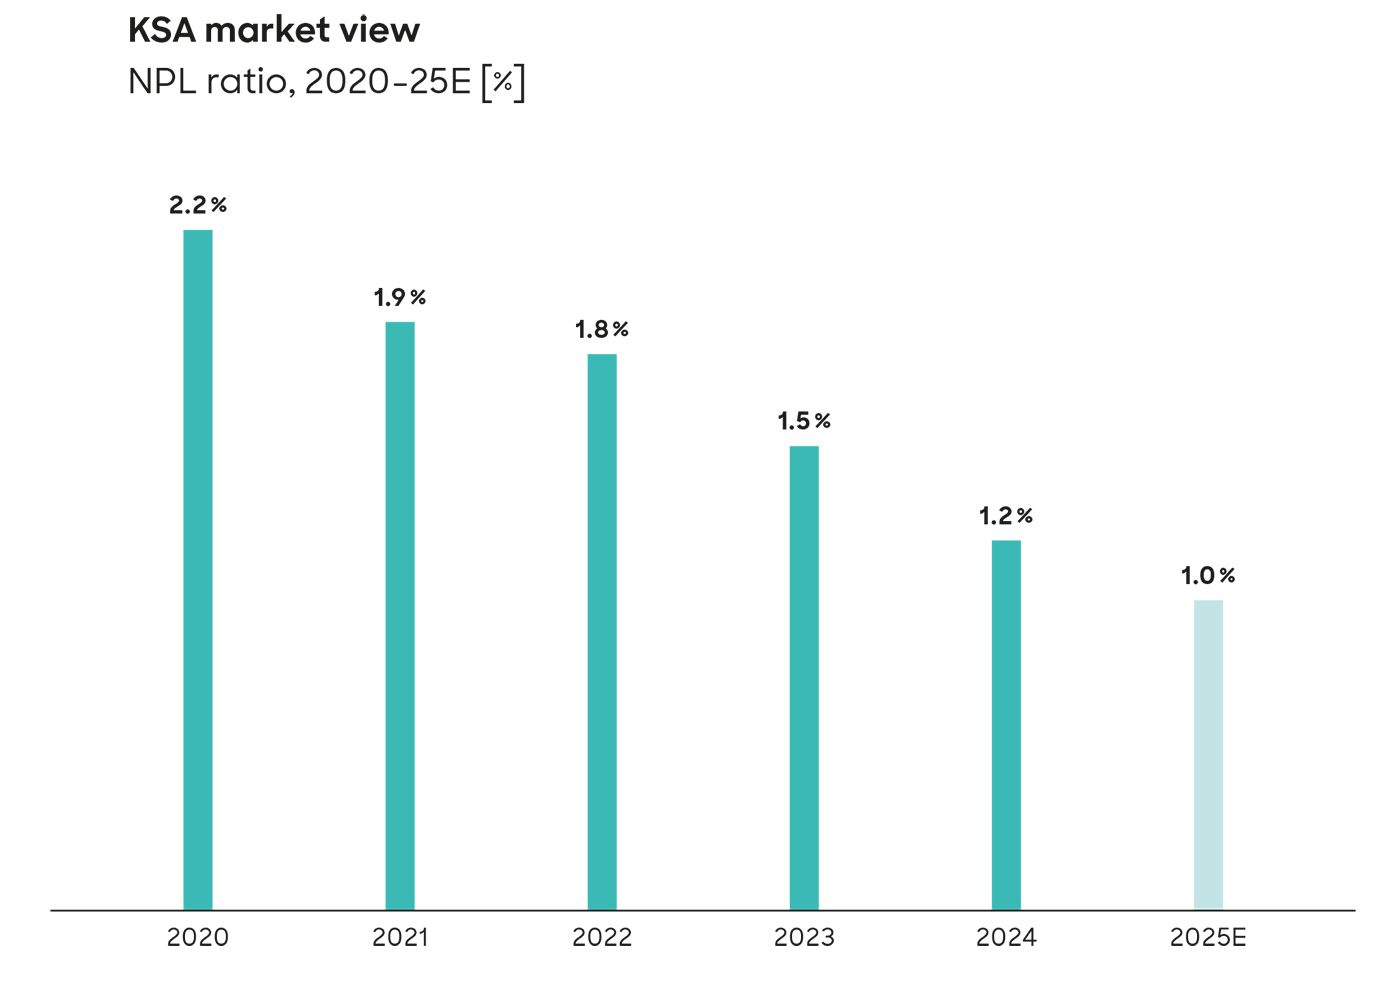
Saudi Arabia exhibits the strongest asset quality metrics among the three markets. Its market-average NPL ratio fell to just 1.2% in 2024, dropping further to 1.0% in 2025. Roland Berger credits tighter lending standards from the Saudi Arabia Monetary Authority and the economic diversification pushed by Vision 2030. Still, the report cautions that for some banks, much of this improvement came from accelerated write-offs rather than genuine loan recovery.
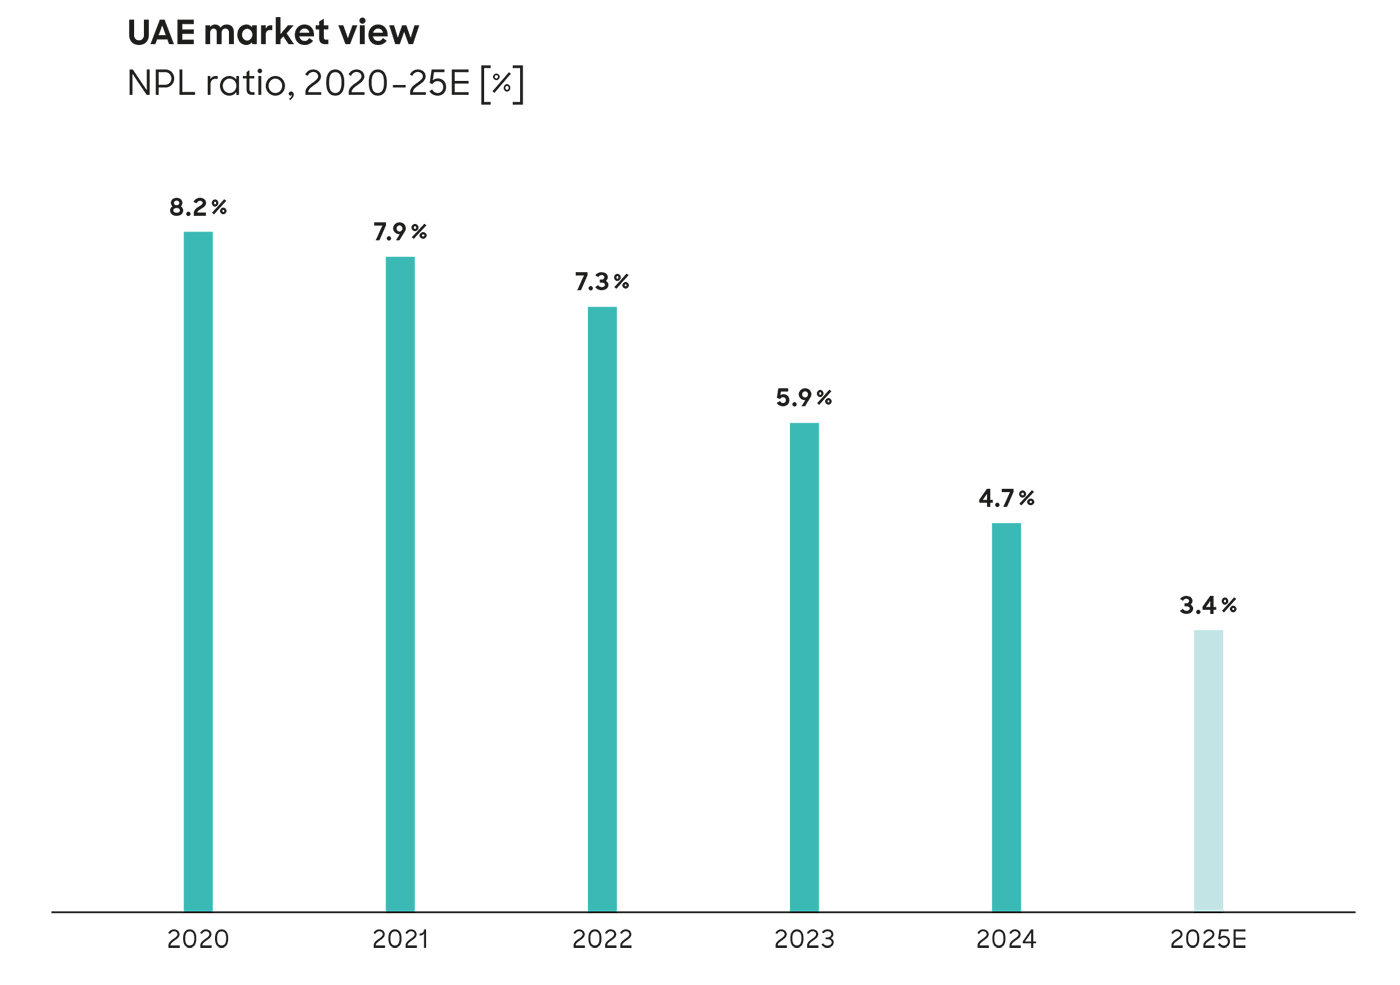
The UAE, meanwhile, has also made steady progress, cutting its sector-wide NPL ratio from a peak of 8.2% in 2020 to 4.7% by the end of 2024, with a further decline to around 3.3% in 2025. The report attributes this to a fast economic rebound and healthy new lending activity, along with banks actively selling off troubled loan portfolios to international investors. Even so, smaller UAE banks continue to carry NPL ratios well above the sector average, particularly where they are exposed to real estate.
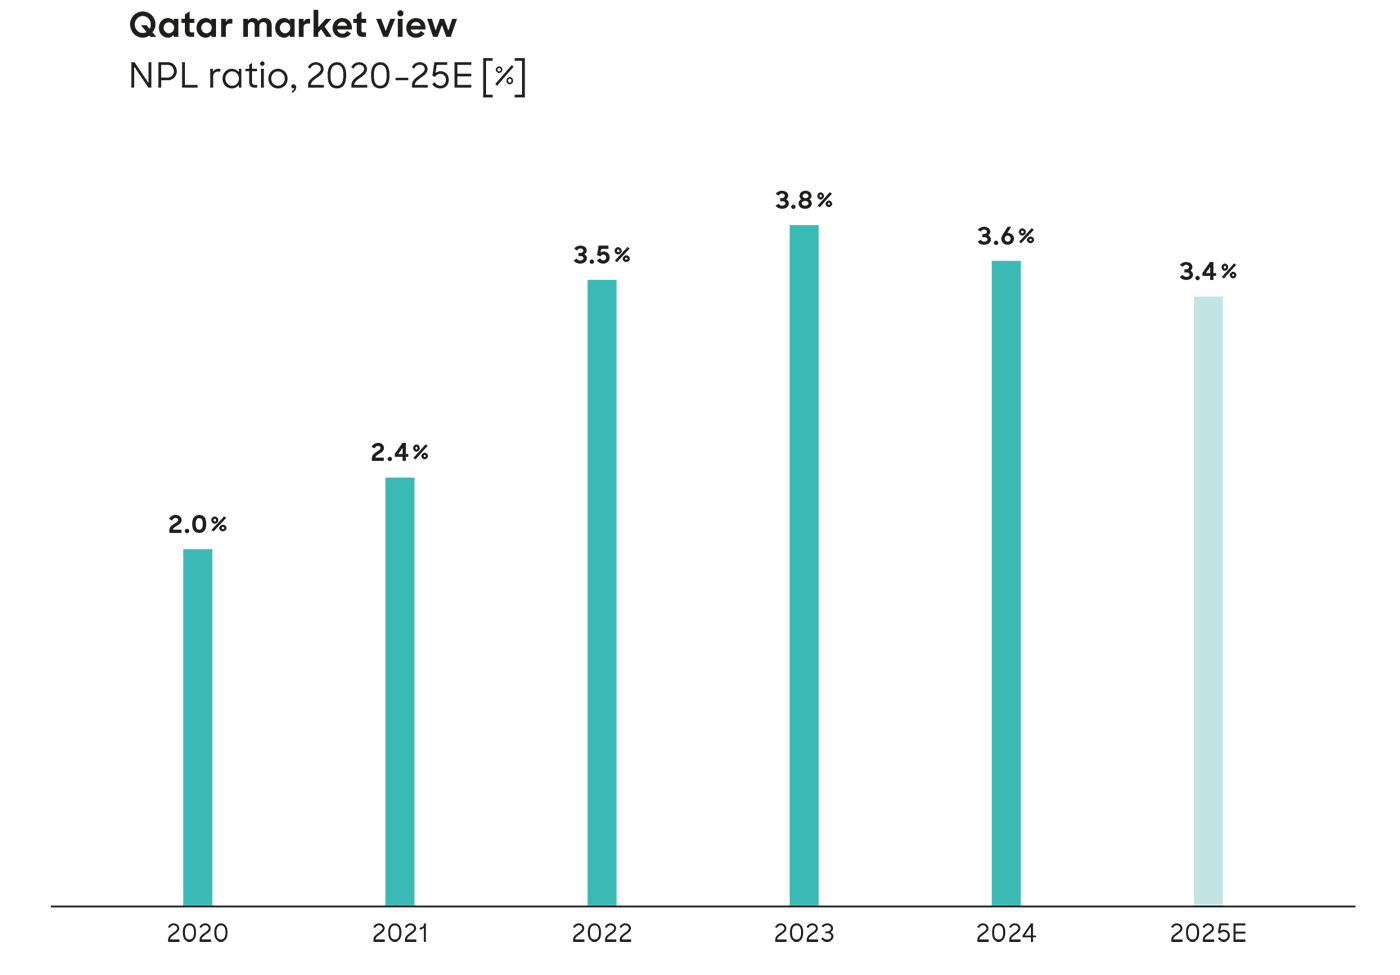
Qatar, for its part, stands apart. Its NPL ratio rose from 2.0% in 2020 to a peak of 3.8% in 2023, before easing slightly to 3.6% in 2024. Roland Berger links this rise to real estate oversupply following the 2022 World Cup, along with exposure to the trading and small business sectors. The firm describes Qatar’s trajectory as the most uncertain of the three markets, even as early signs of stabilization emerged in 2025.
A call for action
The report argues that several forces are converging to make this a critical moment for Gulf banks. Credit volumes have grown rapidly in recent years, driven by large national projects such as Vision 2030 in Saudi Arabia and infrastructure tied to Qatar’s North Field gas expansion. That means even a stable NPL ratio now points to a much larger pool of troubled loans than in the past, since the overall size of loan books has grown so much.
Regulators have also been raising the bar in recent years. For example, central banks in Saudi Arabia, the UAE, and Qatar are moving toward stricter provisioning rules aligned with international accounting standard IFRS 9, along with more rigorous stress testing. The write-offs banks have relied on to lower their ratios cannot continue indefinitely, meaning the underlying quality of credit management will soon matter more than it has in recent years.
Geopolitical tension in the Middle East adds a further layer of risk, with the potential to continue seriously straining small businesses, retail borrowers, and trade-linked companies in particular.
A two-track approach
To build lasting resilience, Roland Berger recommends that banks pursue two strategies at once. The first is proactive: Focus on building the technology-enabled organizational and process infrastructure that prevents NPLs from forming in the first place, or catches them early enough to intervene before they crystallize. The second is reactive: Resolving loans that are already troubled through restructuring, liquidity support, and – when necessary – asset sales or write-offs.
According to the report, most Gulf banks already have some version of both approaches in place, but few apply them with real depth. Proactive measures generally take 12 to 24 months to show up in the numbers, the report notes, while reactive measures alone cannot stop new bad loans from forming. Banks that treat today’s lower NPL ratios as a finished job, rather than an ongoing effort, risk falling behind when the credit cycle eventually turns.
“The window of low NPLs is an opportunity, not a destination – banks that wait will pay”, said Luca Turba, partner at Roland Berger.