Saudi banks post record profits as lending shifts from households to businesses

Saudi Arabia’s listed banks have delivered a strong first half, with combined profits reaching SR48.8 billion despite a sharp slowdown in credit growth. Osamah Alfadda, Mohammed Altuwaijri and Hadeel Al-Attari from Impactors walk through the highlights and outline what’s ahead for the industry.
In H1 of 2026, Saudi Arabia’s listed banks have recently reported one of their best half-year performances on record. Dividends were increased, and analysts expressed their approval.
Consequently, every headline interpreted these results as positive news for shareholders. However, at Impactors, we view these results differently. A bank’s financial results provide detailed public insight into who can access money in the kingdom, under what conditions, and where capital is likely to flow next.
For anyone running a business in Saudi Arabia, managing a ministry program, or considering expansion of a family company, the first-half disclosures provide answers to questions far more significant than whether to purchase bank shares. Unfortunately, very few people read them with this perspective.
The scoreboard
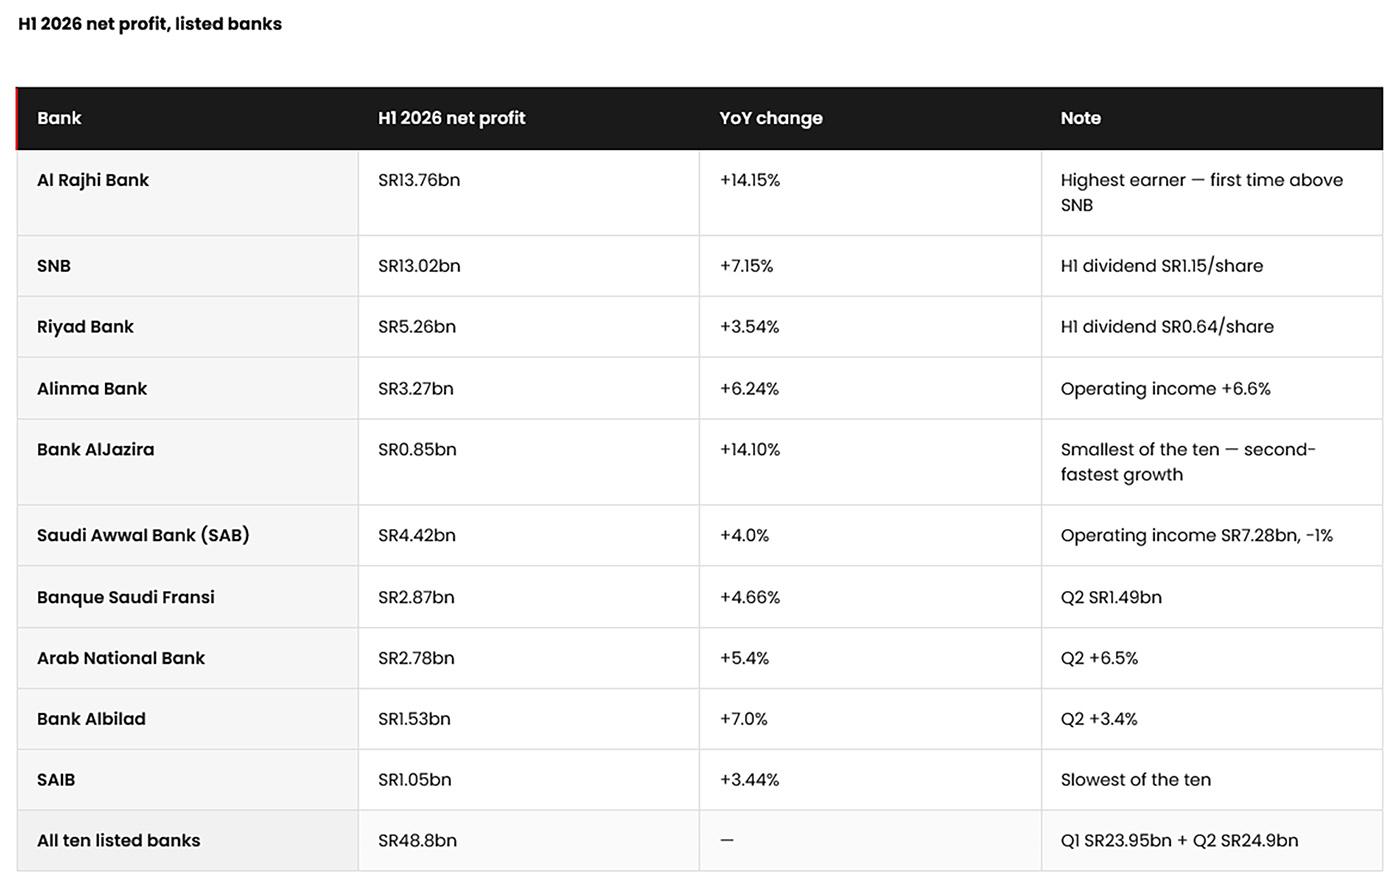
The facts are quickly told. The ten listed banks collectively earned SR48.8 billion in the first half of the year, largely due to increased financing income and fees, and lower funding costs. Growth rates varied significantly, ranging from 3.44 percent at SAIB to 14.15 percent at Al Rajhi, with the fastest-growing bank expanding four times as quickly as the slowest.
One noteworthy result that warrants more attention is Bank AlJazira, the smallest bank among the ten in terms of profits, which achieved 14.10 percent profit growth, just shy of Al Rajhi’s growth. This means that the two fastest-growing banks in the Kingdom occupy opposite ends of the size spectrum, highlighting that the winners in this half were not determined by scale.
The number underneath the number
Let’s start with a key figure that much of July’s coverage got wrong. Several reports indicated that bank credit was “up 16.2 percent year-on-year” – a figure that actually corresponds to May 2025, not May 2026.
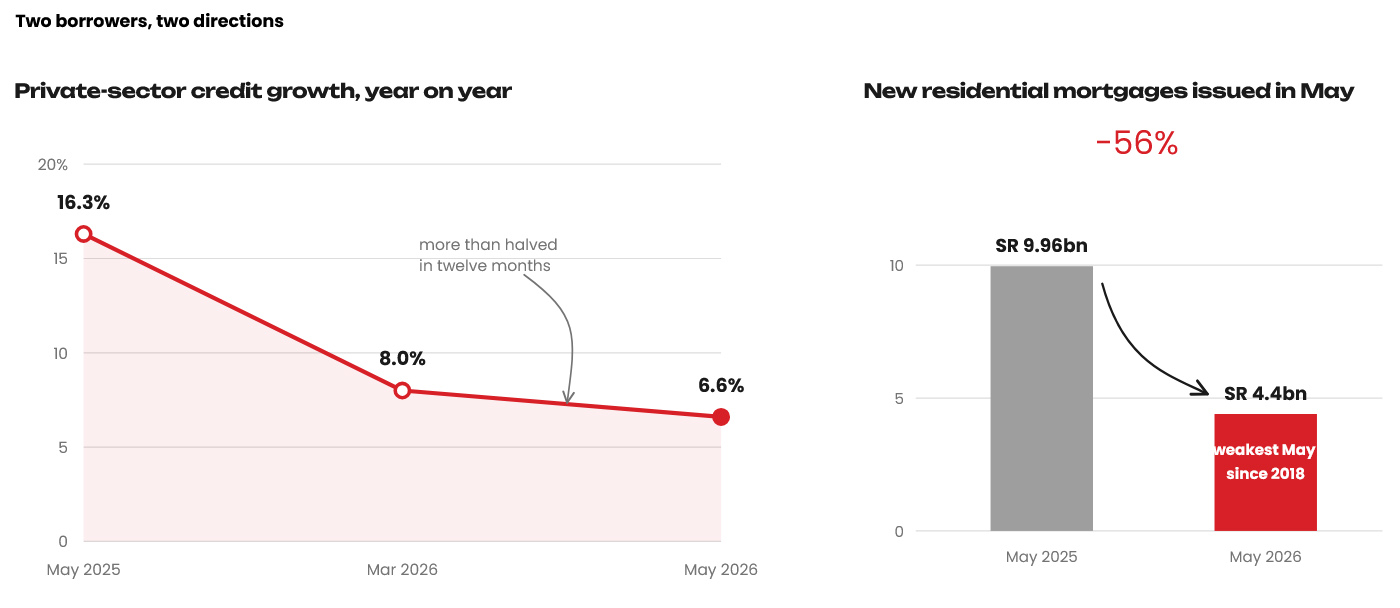
According to SAMA’s May 2026 bulletin, credit to the private sector stands at SR3.2 trillion, reflecting only 6.6 percent year-on-year growth. The real story lies in this deceleration: credit growth was consistently between 16 and 18 percent for much of last year, slowed to around 8 percent by March, and further decreased to 6.6 percent by May, holding at 6.8 percent in June. From January to May, lending grew by only 2.2 percent, less than half the pace observed during the same period in 2025.
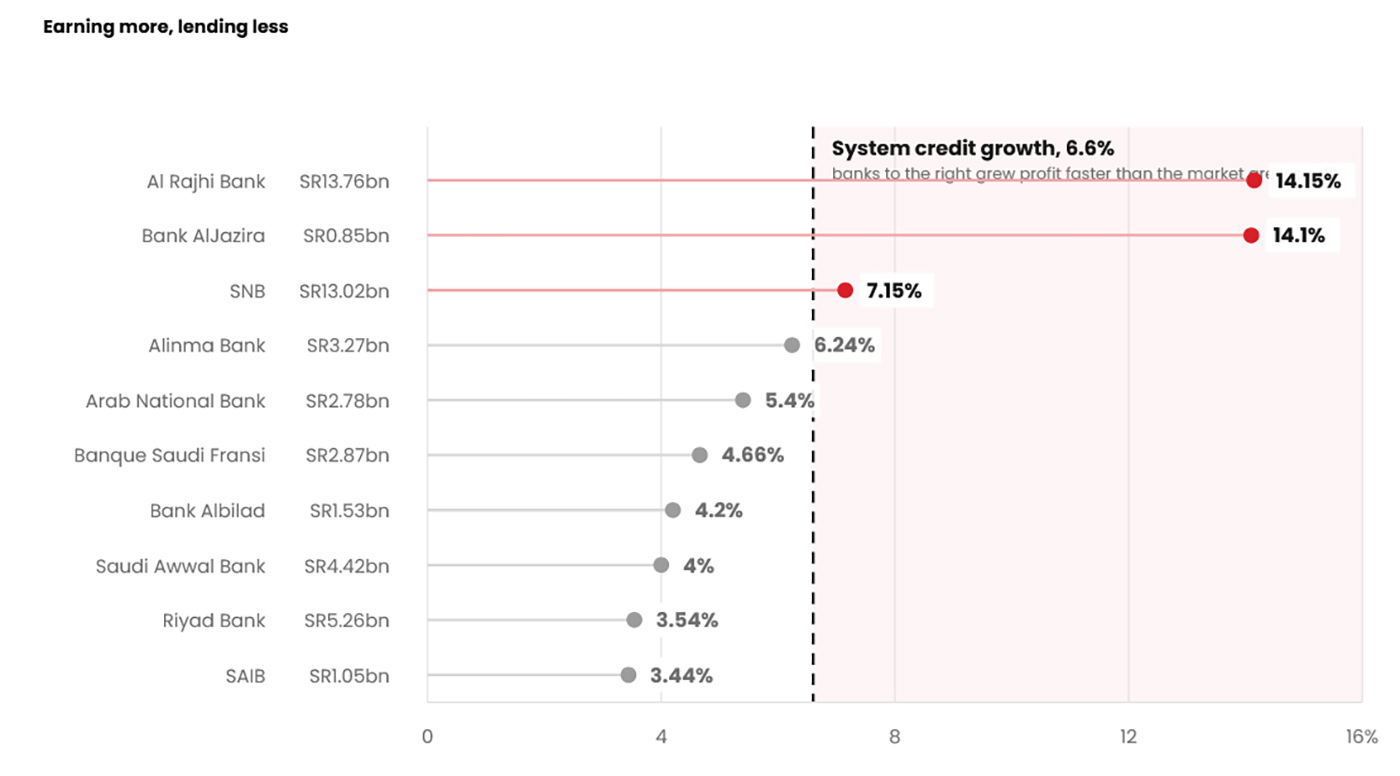
So how did banks report record profits while lending slowed down significantly? The impact of the slowdown was not evenly distributed; it mostly affected one type of borrower: households.
In May, new residential mortgages amounted to SR4.4 billion, a significant decrease from SR9.96 billion a year earlier. This marks the weakest performance for May since 2018. In contrast, corporate credit continues to grow: business lending has increased its share of the overall loan portfolio for over a year, reaching 55.4 percent of all credit by May 2025, up from 52.9 percent.
Corporate lending is growing at twice the rate of personal lending. The same tilt appears in small-business credit: facilities to micro, small and medium enterprises reached SR420.7 billion by mid-2025, up 37 percent year on year, with banks providing 94.7 percent of it.
In simple terms, over the past eighteen months, the Saudi financial landscape has gradually shifted from focusing on households to prioritizing businesses. For those selling to consumers, this shift presents a demand challenge that may be evident before it reflects in retail data. Conversely, if you are borrowing as a company, you are now the customer that banks are eager to attract.
If you sell to consumers: the early warning
Household credit serves as a leading indicator of household spending. The recent mortgage collapse has already impacted the property market, with villa prices dropping by 9.7 percent over the year ending in June, despite a 1.3 percent increase in the overall real estate index. Moreover, sales data from July has shown weakness across most categories. In response, the state has launched a first-time homebuyer program last month ‘Alternative Financing’ with REDF, SNB, and NHC, with instalments starting at SR699 per month to deliberately revive the mortgage market.
While we wouldn’t classify this situation as a full-blown consumer downturn just yet – since unemployment remains at a record low of 2.8 percent, and summer travel is generating spending that will partially continue – businesses planning for 2027 based on 2024’s credit-driven growth expectations may find themselves operating in a market that is no longer relevant. The reality is that demand is shifting from credit-financed purchases to consumption based on salaries, and the companies that adapt first will have the most pricing power.
If you borrow: this is the window
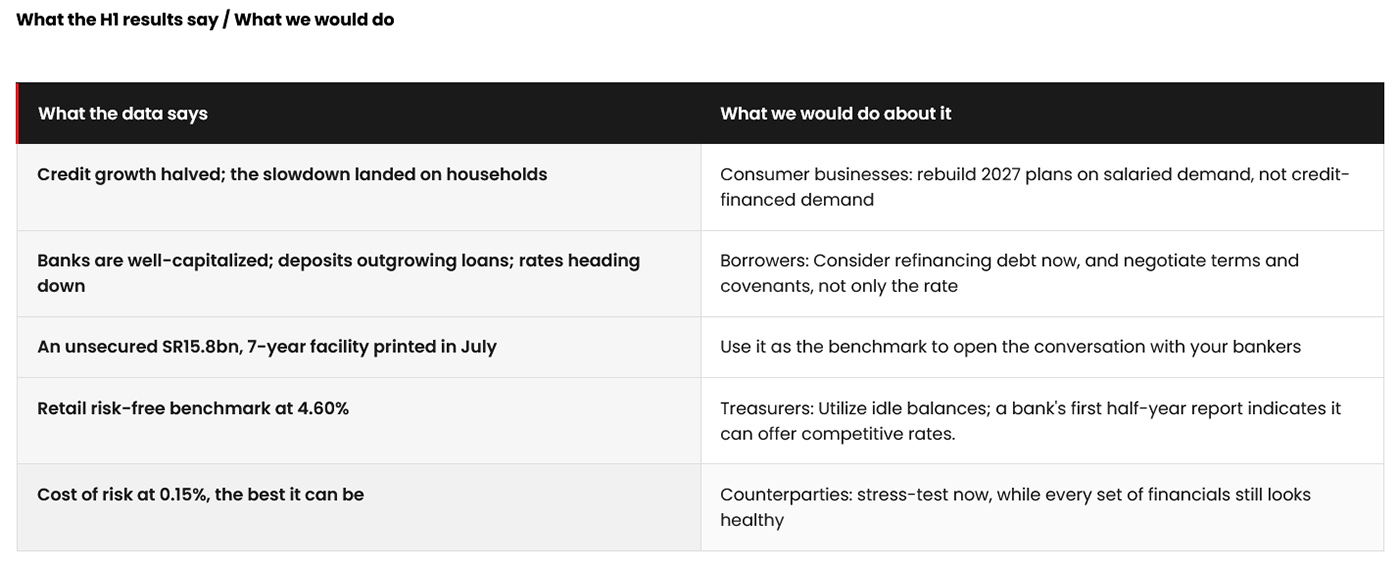
For corporate borrowers, the first half of the year reflects unusually favorable conditions for three key reasons. First, banks have capital to deploy. Deposits have grown faster than loans in the first quarter, with a growth rate of 3.9 percent compared to 1.6 percent for loans. This dynamic has pulled the sector’s loans-to-deposits ratio down from 106.5 percent to 104.1 percent, according to analysts’ definitions.
Meanwhile, SAMA’s regulatory ratio, which considers stable funding more broadly, is near 79 percent. Both ratios are accurate as they measure different aspects. Additionally, funding costs have eased, and roughly 100 basis points in rate cuts are expected by the end of 2026 as SAMA monitors the Federal Reserve.
Second, this appetite for lending is evident in real transactions, not just aggregate numbers. Recently, Saudi Energy signed a SR15.8 billion, seven-year unsecured Murabaha facility with seven local banks for general corporate purposes. This indicates that such favorable terms are typically offered at the beginning of a lending cycle, not at the end.
Third, banks are not the only players in the market. Saudi issuers raised $49.3 billion in bonds and sukuk during the first half of the year, accounting for 48 percent of all GCC issuance. Corporates, rather than sovereign entities, made up nearly two-thirds of the region’s total. The sovereign itself utilized July to retire SR17.1 billion of near-term sukuk while reissuing bonds with maturities extending to 2041, strategically lengthening its debt profile while demand is strong. Companies can view this as a model for their own funding strategies.
The practical conclusion is this: If your plans involve debt, expansion, acquisition, or refinancing, the terms available in the next two to three quarters are likely to be the best of this cycle. Banks are competing for quality corporate risks precisely because the mortgage sector, which once absorbed their liquidity, has stalled. Opportunities like this may close without warning.
The overlooked line: your idle cash
One often-overlooked consequence of the deposit race is that banks now prioritize deposits almost as much as they do borrowers. As banks compete for stable funding, term deposits have seen significant growth, particularly with the government’s retail sukuk program offering a rate of 4.70 percent as of August. This rate effectively serves as the Kingdom’s risk-free retail benchmark, influencing the pricing of many financial products.
For a corporate treasury maintaining substantial balances in current accounts, this means they are essentially giving up potential earnings to their bank. With an average idle balance of SR50 million, the difference between earning zero interest and securing a negotiated deposit rate represents a substantial amount of money. In the first half of the year, banks’ own results indicate that they are in a position to pay these higher rates. SAMA’s June data show the shift is already under way: time and savings deposits rose 25 percent year on year to SR1.375 trillion, while demand deposits fell 3.2 percent.
What to watch in H2
An overview of key metrics we anticipate leaders should keep a close eye on:
Monthly mortgage issuance
This is the best indicator of household credit appetite and whether the SR699-a-month program will restart it. If monthly issuance falls below SR5 billion in the second half, it would confirm that the shift in trends is structural rather than seasonal.
Provisions
The cost of risk for the sector was just 0.15% in Q1, with non-performing loans (NPLs) ranging from 0.9% to 1.1%, indicating unusually low risk levels. If provisions increase in Q3, it may suggest that H1’s record profits were inflated due to timing issues.
The MSME experiment
We need to observe whether MSME growth – 37 percent year on year through mid-2025 – can sustain itself through its first challenging quarter or if it was merely a yield trade.
The rate path
Anticipated rate cuts of about 100 basis points by the end of 2026 could compress bank margins and further reduce corporate debt costs, benefiting borrowers. However, this will pose a challenge for banks’ fee income.